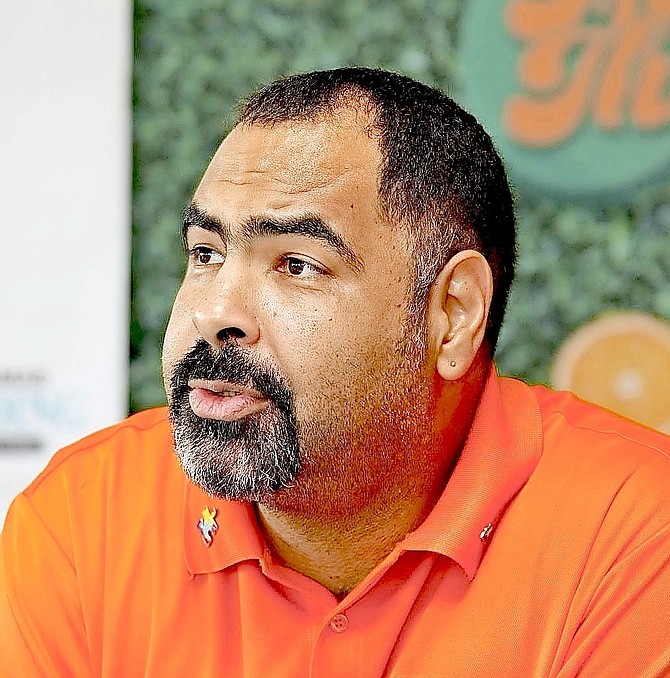
Gowon Bowe
BY NEIL HARTNELL
TRIBUNE Business Editor
nhartnell@tribunemedia.net
MORTGAGE lending is “in life support” until Bahamians correct their borrowing habits and over-indebtedness, a banker warned yesterday, after less than half of new home loan applications were approved during the 2026 first-half.
Gowon Bowe, Fidelity Bank (Bahamas) chief executive, told Tribune Business that the mortgage market has not seen “any life breathed into it” with the ability of many home buyers to access loans impaired by high levels of existing debt and poor credit qualities and histories.
Speaking after the Central Bank of The Bahamas revealed that mortgage applications for the six months to end-June fell by 5.9 percent year-over-year, while the approval rate “softened by 8.3 percentage points” to just 45.6 percent, he said: “Mortgages have not had any life breathed into that sector.
“That’s literally a sector on life support. Until we see a correction of credit quality on consumer loans, we will not see any improvement on the mortgage side because people have gorged themselves on the consumer side. They are virtually counting themselves out of the mortgage process.
“If they have $100,000 in unsecured consumer debt, getting a mortgage loan for $250,000, which is the minimum they need to have, will be quite a challenge, and this is what the survey demonstrates.” The reduction in new mortgage approvals threatens to further slow the Bahamian housing market, impacting not just banks but realtors, attorneys and all industries that service the home sector.
The Central Bank’s 2026 first half lending conditions survey, results for which were unveiled yesterday as part of the regulator’s third quarter economic update, revealed that close to 15 percent of loan applications - between one in six and one in seven - were denied during the six months to end-June 2026.
The data indicated a slight softening in the market, with total new loan applications received by Bahamian commercial banks - some 18,291 - down by 4.1 percent for the 2026 first half compared to the year-before period. Total approved applications stood at 15,604, meaning 2,658 were rejected for an 85.3 percent approval rate, with the number approved some 0.3 percent less than in 2025.
“Bank lending conditions moderated during the first half of 2026, relative to the comparative period of 2025, underpinned by a decline in credit demand,” the Central Bank said.
“Approximately 14.7 percent of loan applications received were denied, with the main reasons cited including ‘other’ miscellaneous reasons, high debt service ratio (DSR), insufficient job tenure and prior loan delinquencies.”
Consumer loan applications, which accounted for 94 percent of the total submitted, were down by 4.6 percent compared to the 2025 first half which represented a “turnaround” from the 14.8 percent growth enjoyed last year. However, this was balanced by a 3.7 percentage rise in the 2026 first-half approval rate to 86.7 percent.
However, Mr Bowe described as “most positive” the 22.3 percent increase in commercial loan applications during the 2026 first half, suggesting this was a sign of growing business confidence and more persons starting their own businesses.
The jump represented “a reversal from the 41.3 percent contraction last year, due to higher demand in New Providence and the Family Islands”, and the Central Bank said the approval rate for new business credit applications also rose by 2.7 percentage points to 91.2 percent compared to the 2025 first-half.
“I think that what is most positive, and what I’m observing in my institution across the country, is commercial loan applications are increasing,” Mr Bowe told Tribune Business. “It’s a smaller base, but we are seeing more persons getting into enterprise and seeking financing.”
He explained the high approval rate by disclosing that many corporate loan candidates have already “gone through a vetting exercise” through the likes of the Small Business Development Centre (SBDC) to ensure their business plans are ready to be presented to the banks and other financiers.
“What’s positive is commercial borrowing is increasing, which indicates businesses are back in a position of confidence of borrowing for expansion purposes. That is something that should be noted and supported by the Government,” Mr Bowe added.
“Statistics and information like this should be the impetus for the Ministry of Economic Affairs to understand where the loan opportunities are coming from and make sure government policies are aligned to support these businesses in their development.”
Turning to the survey findings as a whole, the Fidelity Bank (Bahamas) chief added: “What they [the Central Bank] have summarised is wholly consistent. Nothing is surprising. When we look at it, we know the overall credit quality in the country is not improving in the sense people are over-leveraged. It’s not going backwards, but it’s not improving.
“The number of applications is down and the number of applications approved is down. The amount of people simply not having the capacity to extend their borrowing - in the absence of capacity there’s less willingness to even apply.” Mr Bowe said a turnaround in the Bahamian lending environment will likely only occur when there is a major positive economic shock.
“When we look at the last 18 months, there hasn’t been any positive economic shock or negative economic shock, which means persons are in a state of rehabilitation and means the process is flat with the application volumes and dollar values.”
Some 27 percent of loan denials were because applicants’ debt service ratios were already too high, raising doubts about their ability to take on new credit and repay it. The absence of sufficient loan collateral; inability to make the required down payment; under-employment; a past history of loan delinquency; inability to verify income; and lack of time on current job were other factors.
Debt consolidation accounted for 17.3 percent of consumer loan applications during the 2026 first half, with credit cards and private cars taking a 24.3 percent and 13.6 percent share, respectively.
John Rolle, the Central Bank governor, said of the survey findings: “The latest lending conditions survey revealed that over the first half of the year, although the number of credit applications decreased slightly, banks approved almost the same volume of requests as in 2025, resulting in a boost in the share of borrowers who were approved.”
He added that domestic credit expansion, led by private sector lending, had expanded at a faster pace through the first nine months of 2026 at 6.1 percent on “an adjusted basis” compared to 4.3 percent during the same period last year.
“This included accelerated growth in consumer credit, and slightly faster residential mortgage gains, contrasting with a smaller advance in commercial credit. Lending risks further subsided compared to 2025,” Mr Rolle said.
“In particular, the non-performing loans rate, or share of facilities falling three or more months behind in payments, decreased to 4.5 percent in September 2026 from 5 percent at the same point in 2025.”


Comments
Use the comment form below to begin a discussion about this content.
Sign in to comment
OpenID